 11
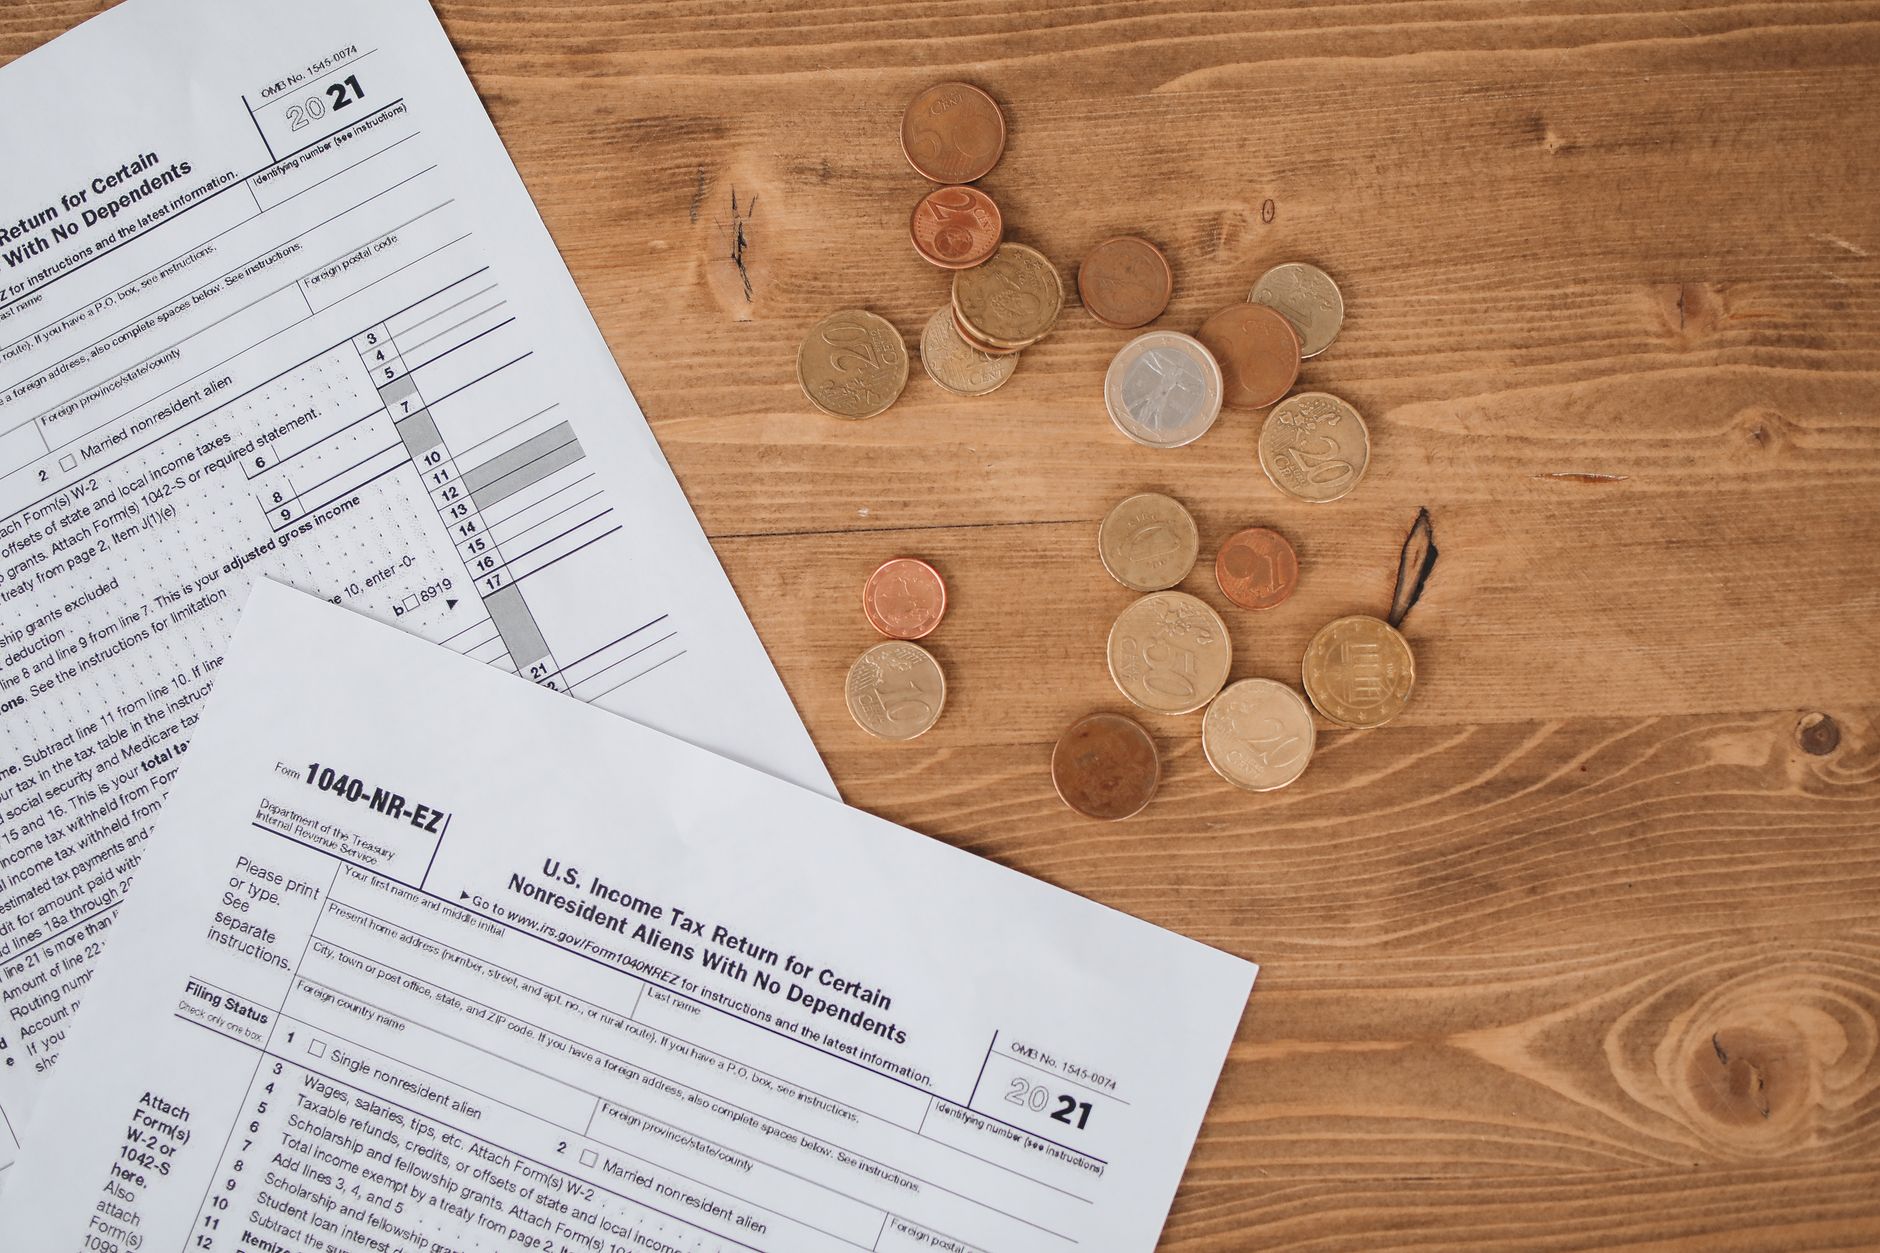
IRS tax rule changes are set to benefit many workers, allowing them to claim up to $25,000 in new deductions. This adjustment could significantly impact personal finances.
The IRS has recently implemented significant tax rule changes that may benefit many taxpayers. These changes provide opportunities for workers to claim deductions of up to $25,000, which could greatly impact their overall tax liability.
Among the notable adjustments are:
These IRS tax rule changes aim to provide financial relief and encourage spending among workers. Taxpayers should review these new provisions to ensure they maximize their potential deductions this filing season.
The recent IRS tax rule changes have opened the door for many taxpayers to benefit from new deductions, but not everyone will qualify. Understanding who is eligible is essential for maximizing potential savings.
To qualify for the new deductions, individuals must meet specific criteria, including:
It is crucial for taxpayers to review their eligibility thoroughly to take full advantage of the recent IRS tax rule changes and claim up to $25,000 in deductions effectively.
To effectively claim your deductions under the recent IRS tax rule changes, it is essential to follow a few key steps. Understanding the process can maximize your potential benefits and ensure compliance with tax regulations.
First, gather all necessary documentation to support your deduction claims. This includes:
Next, familiarize yourself with the specific deductions available to you. Depending on your situation, you might qualify for:
Lastly, consider consulting a tax professional who can provide tailored advice and help navigate the complexities of the IRS tax rule changes, ensuring you optimize your deductions up to $25,000.
The recent IRS tax rule changes are poised to significantly impact the finances of many taxpayers. With the potential to claim up to $25,000 in deductions, individuals may experience a notable reduction in their taxable income. This could lead to substantial savings, particularly for those who are eligible for the new deductions.
For many workers, understanding how these changes affect their financial situation is crucial. Here are some key considerations:
Overall, the impact of the IRS tax rule changes can be substantial, making it essential for taxpayers to stay informed and take action.
Photo by Polina Tankilevitch on Pexels
NSE IPO Opening Date: A Clear Guide to Investment Opportunities · XRP price outlook: Best proven strategies for investors · NSE sectoral benchmarks: Are they the best for investors?